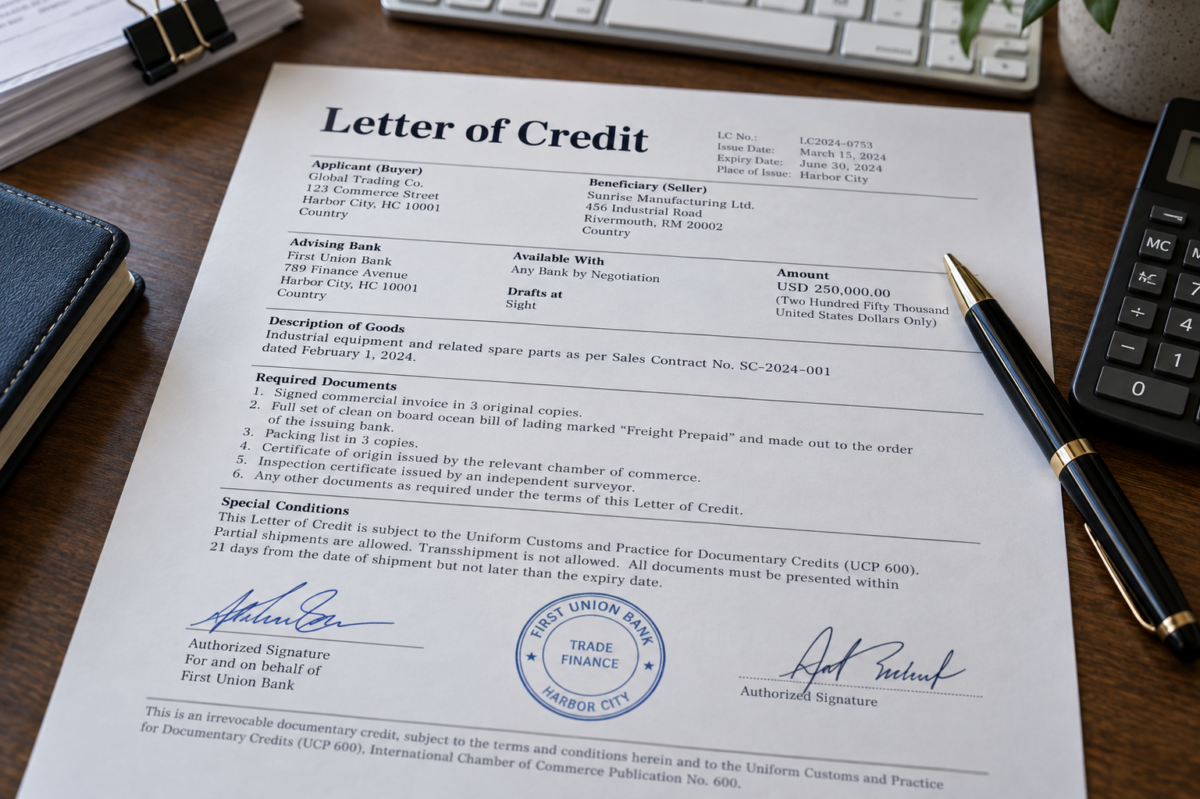


Letter of credit fees are the charges banks apply for issuing, advising, confirming or processing an LC. The total depends on the transaction, its duration, the banks involved and the services required. A quoted issuance percentage is not necessarily the full cost. Buyers should also assess funding, currency conversion and the commercial effect of any cash margin.
There is no single reliable percentage that represents every LC worldwide. A short, unconfirmed credit and a longer confirmed credit expose banks to different risks. Minimum fees and charging periods can also make two apparently similar quotations produce very different totals.
Bank charges are set by the financial institutions, but their final impact can also depend on how well the purchase is organised. MWT helps buyers coordinate the supplier, inspection and shipping milestones that underpin the LC.
By checking document feasibility and deadlines earlier, an importer may reduce avoidable last-minute changes and operational surprises; this is not a guarantee of lower bank fees.
The fees to include in your comparison
Ask for a written breakdown showing which charges are fixed, percentage-based, time-based or payable for each event. The trade finance fee schedule published by Siam Commercial Bank illustrates how LC services are charged separately; its local tariff should not be treated as a quote for your transaction.
Confirm the fee currency and whether charges belong to the buyer or the beneficiary.
| Fee category | What it relates to | Question for the bank |
| Issuance | Opening the LC and providing the undertaking | What amount, rate, period and minimum apply? |
| Advising | Authenticating and notifying the credit | Is the charge included or billed separately overseas? |
| Confirmation | An additional bank payment undertaking | Is it required and what risk period is priced? |
| Document handling | Examination or processing of a presentation | Is the fee per presentation or per drawing? |
| Amendment | Changing the credit | Does an extension or increase also add commission? |
| Discrepancy | Handling a non-complying presentation | Who is charged and on what basis? |
| Messaging and delivery | Bank communications and document dispatch | Are SWIFT and courier costs additional? |
| Financing | Advancing funds or funding a deferred obligation | What rate, period and additional charges apply? |
Not every transaction incurs every fee. A confirmation charge should not be added automatically to an unconfirmed LC budget, and an amendment fee is only relevant when a change is made. Nevertheless, foreseeable changes belong in a contingency estimate.
Read the charging basis before comparing rates
A bank might quote a percentage per quarter or part of a quarter, while another quotes an annual rate applied to an agreed period. These figures cannot be compared without converting them to the same transaction assumptions.
Also check whether the fee applies to the original amount, the outstanding balance or an increased amount after amendment. A minimum fee can dominate the calculation for a small order. Partial drawings may generate several handling charges even if the total order value remains unchanged.
Confirmation pricing can depend on the issuing bank, country exposure and duration of the undertaking. The relevant duration may extend beyond the shipment date or the LC expiry, particularly where payment is deferred. Ask the confirming bank to identify the priced period explicitly.
A worked example of letter of credit fees
The following numbers are invented solely to demonstrate the calculation. They are not a bank tariff, an MWT quotation or an estimate of prevailing market rates.
Assume a USD 100,000 order, an unconfirmed LC, one presentation and an issuance fee of 0.30% for each three-month period or part thereof, with a USD 250 minimum. Assume the credit initially falls within one charging period.
| Cost item | Illustrative calculation | Amount |
| Issuance | Higher of USD 100,000 × 0.30% or USD 250 | USD 300 |
| Advising | Assumed fixed fee | USD 100 |
| Document handling | One presentation | USD 150 |
| Messaging and courier | Assumed combined charge | USD 50 |
| Total before changes | Sum of the four items | USD 600 |
The initial total is 0.60% of the order value. If an amendment adds USD 100, the total becomes USD 700, or 0.70%. Under the assumed tariff, an extension into a second charging period could add another USD 300 if the full amount remains outstanding and the same basis applies. The total would then become USD 1,000.
This example excludes confirmation, financing, exchange costs, taxes and any other charge not expressly listed. It demonstrates why a low headline percentage does not by itself tell you the final cost.
Include the cost of funding and tied-up cash
If your bank requires a cash margin, that amount may be unavailable for other purchases. It is not the same thing as a fee, but it affects your working capital. Likewise, financing a payment or discounting a deferred receivable creates a separate interest cost.
For a simple hypothetical illustration, borrowing USD 100,000 for 60 days at 6% per year on a 360-day basis produces USD 1,000 of interest: 100,000 × 6% × 60 ÷ 360. Actual financing depends on the agreed rate, day-count convention and additional terms. Do not insert this illustrative rate into a budget without a bank quotation.
Compare payment options using the full commercial picture. A supplier may offer a different product price for sight payment, deferred payment or an advance. The cheapest banking charge is not necessarily attached to the lowest total purchasing cost.
Who pays and how can you avoid unnecessary charges
Buyer and seller should agree the allocation in the commercial terms and ensure the credit reflects it. Pay attention to charges outside the issuing bank’s country, confirmation charges and deductions from the supplier’s proceeds. A misunderstanding may lead the supplier to request a higher price or an amendment after issuance.
To reduce avoidable costs, review the draft with the supplier before opening, align dates with production and request only useful documents. A realistic shipping window is usually better than repeatedly extending an optimistic one. Check whether planned split deliveries create multiple presentation fees.
Track the reasons for amendments and discrepancies across repeat orders. If changes repeatedly originate from late production updates, the corrective action belongs in supplier follow-up. If documents are repeatedly unavailable on time, revise the preparation process before the next order.
This is an area where MWT adds practical value: our team connects supplier updates, production progress, quality checks and shipping dates, so the buyer can detect issues that might otherwise prompt amendments or repeated document presentations.
MWT can help prepare the operational facts for discussions with the bank, but bank quotations, credit approval, issuance and documentary examination remain the banks’ responsibility.
MWT’s supplier management service helps buyers connect purchasing, production, inspections and document availability to the proposed LC schedule. This operational coordination can help reveal avoidable sources of amendment or discrepancy charges before they arise, though savings cannot be guaranteed. Banks alone quote their charges, assess facilities, issue or amend credits and examine documentary presentations.
Two practical use cases for budgeting
Both scenarios are hypothetical. The amounts below are calculation assumptions, not market tariffs or MWT client results.
A small order affected by a minimum fee
A buyer compares LC costs for a USD 20,000 order. At an assumed issuance rate of 0.30%, the calculated charge is USD 60. If the bank applies a USD 250 minimum, the issuance charge becomes 1.25% of the order value before any other fees. The buyer includes that amount in its sourcing cost comparison rather than budgeting solely from the headline percentage.
A quality correction leads to an extension
A pre-shipment inspection identifies defects requiring rework. Production will miss the LC deadline, so the parties request an extension. The buyer asks the bank whether this triggers both an amendment fee and another charging period.
Planning product quality control earlier can leave more time for corrections, though it cannot guarantee that amendments or extra fees will be avoided.
Frequently asked questions about LC fees
Are letter of credit fees negotiable
Some may be, depending on the bank, relationship and transaction volume. Ask for a transaction-specific quotation and compare the same assumptions, including third-party charges and minimums.
Does a confirmed LC always cost more
Confirmation is an additional bank service and can add a separate charge. The amount and allocation need to be quoted for the actual transaction; they should not be assumed from a general percentage.
Are fees refunded if the credit is unused
Do not assume so. Issuance and other services may already have been provided. Ask which charges remain payable on cancellation, expiry or non-utilisation before committing.
Contact MWT Sourcing to review the supplier, production, inspection and shipping plan behind your next LC-backed order. We can help prepare a coherent operational schedule before you seek a formal fee quotation and issuance from your bank; banking charges and decisions remain with the financial institutions.